U.S. ports took in more import containers in October than in any month on record, including the 2022 surge. The trucks and warehouses that have to absorb those boxes are tighter than a year ago, and the U.S.-China port fee truce now runs only to January.
Key Takeaways
The previous import record was set in May 2022, at the height of the pandemic shipping crunch. October's new high arrived with far less fanfare, and into a market that has spent most of 2026 losing trucking and warehouse capacity rather than adding it. The record matters less for what it says about demand than for what it asks of everything behind the port gate: drayage, transload space, distribution centers and the long-haul trucks that move freight on to stores before the holiday deadline.
U.S. container imports reached 2,674,808 twenty-foot equivalent units in October, according to Descartes data reported by Reuters on November 11. That was up 16% from a year earlier and the highest volume for any month, edging past the previous record of 2,622,465 TEUs set in May 2022. Imports from China reached 987,805 TEUs, up 22.9% year over year and the highest since January 2025, led by plastic goods, furniture and bedding, and toys, games and sporting goods. Import volume for the first ten months of 2026 was up 2.3% on the same period of 2025.
The geography of the surge is shifting too. Top East and Gulf Coast ports gained share over West Coast gateways in October, and port transit delays rose modestly for the third consecutive month, DC Velocity reported. Jackson Wood, VP of product management for trade regulations at Descartes, said the numbers show that "U.S. maritime trade remains strong, even as trade policy and shipping conditions continue to shift." He also told importers to watch "carrier routing decisions, which can add uncertainty to cost and transit planning."
The port numbers land on a domestic network that is already stretched. The October 2026 Logistics Managers' Index, released November 3, put transportation capacity at 38.0. That was up 3.6 points from September but still deep in contraction, and far below the 54.5 recorded in October 2025. Transportation prices read 88.0, against 61.7 a year earlier. Diesel reached $6.352 a gallon in late October, up 71% year over year, which the report links directly to higher freight rates.
Warehousing tells the same story. Warehousing capacity read 43.5 and has contracted in six of the first nine months of 2026, while warehousing prices rose to 80.7 from 73.5 in September. Inventory costs climbed to 88.8 as retailers stocked up for the holidays, and the report notes that projected imports are still high through much of November. The pressure sits mostly upstream: upstream firms reported transportation utilization of 69.3, against 53.6 for downstream firms, which means the strain falls hardest on the importers, manufacturers and distributors moving boxes off the docks rather than on the stores at the end of the line.
That is the real test of the record. Transportation capacity has contracted in six of the past eight months, according to the same report, so every extra container now competes for the same trucks, chassis and dock doors that were already spoken for.
Trade policy adds a deadline to the capacity problem. USTR had suspended its Section 301 maritime actions against China-linked vessels for one year, from November 10, 2025, through November 9, 2026. In a notice scheduled for Federal Register publication on November 10, it extended that suspension to January 10, 2027, Holland & Knight reported. The pause covers the maritime service fees and the additional duties on Chinese ship-to-shore cranes and other cargo handling equipment. During the suspension, no party accrues liability for the port fees.
USTR has said only that it will decide before January 10 whether to extend again or take further action, and the firm advises clients to "treat January 10, 2027, as a live deadline." It also notes that the equipment duties could be decoupled from the vessel fees and return on a separate track. For importers, the timing is awkward: 2027 ocean and drayage contracts are being negotiated now, against a cost line that could reappear three weeks into the new year.
These steps keep a record month at the port from turning into a backlog at the warehouse door.
A record import month would normally read as good news for demand. This one arrives with tight trucks, shrinking warehouse space and a fee truce measured in weeks. The importers that come through peak cleanly will be the ones that planned the miles after the port as carefully as the voyage that got the boxes there.

Guide
When a record month of imports reaches co-packers and contract manufacturers, the ones with shared data and structured workflows can plan labor and space before the containers land. Nulogy shows how brand owners build that visibility with external partners.
Download

Guide
2027 ocean and drayage contracts are being negotiated while the Section 301 port fees could return on January 10. GEP explains how procurement teams use analytics and stronger supplier relationships to get more value from contract portfolios under that kind of cost uncertainty.
Download

Guide
With transportation capacity at 38 and imports still high through November, outside trucks are scarce. IntelliShift shows how fleet operators use routing and operational visibility to move more freight without adding vehicles or headcount.
Download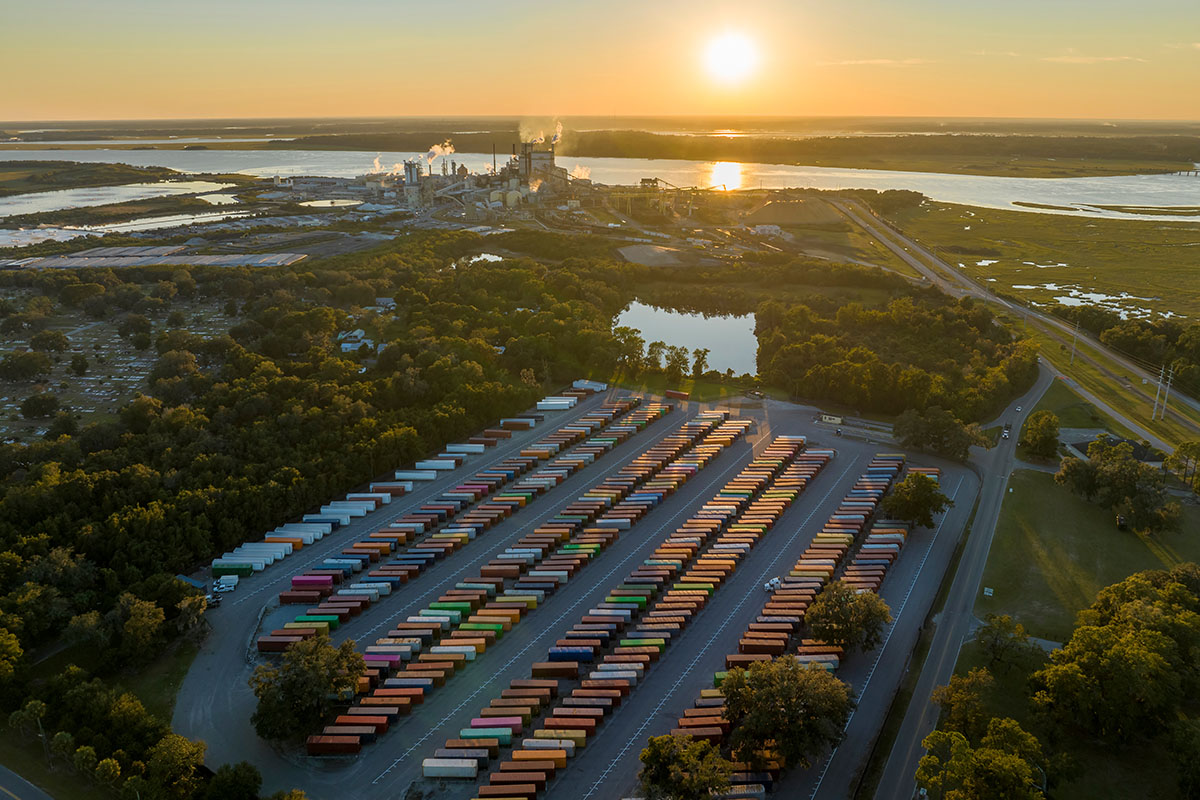
Most U.S. shippers expect to spend more on logistics in 2027, and 52% plan to use more providers rather than fewer. October's aggregate logistics cost index rose at its fastest rate since March 2022, so next year's bids start from a higher base.
U.S. supplier delivery times lengthened in October by the most since July 2022, and manufacturers built input stocks at the fastest rate in four months. With diesel at $6.35 a gallon, every early order now costs more to move.
