September's Logistics Managers' Index shows storage capacity collapsing as holiday stock piles up at manufacturers and wholesalers. The squeeze is landing hardest upstream and on smaller firms.
Key Takeaways
For most of the past three years, finding a place to put inventory was the easy part of logistics. Vacant space was plentiful and landlords were negotiating. September ended that. The latest Logistics Managers' Index shows warehouse capacity shrinking faster than at any point since early 2022, and the shortage is not spread evenly. It is concentrated at the manufacturers and wholesalers holding holiday stock, and it is biting smaller firms harder than large ones.
The September 2026 Logistics Managers' Index, released October 6 by researchers at Colorado State, Arizona State, Rutgers, Florida Atlantic and the University of Nevada, Reno, put warehousing capacity at 39.3, down 14.2 points from August. On the index's scale, any reading below 50 means capacity is contracting, so a reading near 39 signals space disappearing quickly. Warehousing utilization climbed 4.7 points to 64.3 over the same month.
The swing came alongside the strongest overall reading in years. The headline index rose 3.6 points to 70.2, and inventory levels jumped 6.1 points to 58.9 as goods accumulated ahead of the fourth quarter. FreightWaves' analysis of the report notes the capacity reading was the fastest contraction for warehousing space since March 2022, and that aggregate logistics costs of 246.1 were the highest since April of that same year.
The commercial real estate data had been pointing this way. JLL's second-quarter industrial report found national vacancy compressed 60 basis points to 6.8%, which it called the first meaningful contraction since mid-2023. Net absorption reached 99.1 million square feet, nearly double the first quarter, and asking rents rose to $10.45 per square foot as landlords in the tightest markets began regaining pricing leverage. Class A buildings over one million square feet sat at just 5.8% vacancy.
The index splits respondents into upstream firms, mostly manufacturers and wholesalers, and downstream firms, mostly retailers. In September the two groups were living through different markets. Upstream warehousing utilization read 68.4 against 53.8 downstream, a gap the researchers flag as statistically significant. Upstream inventory levels stood at 61.4 versus 53.8, and upstream inventory costs at 80.9 versus 76.9. The report says upstream firms are holding stock until it moves to retailers around mid-October.
Import volumes explain why so much is still in the pipeline. The National Retail Federation's Global Port Tracker, as reported by The Maritime Executive, raised its September forecast to 2.31 million TEU, the busiest month of the year, up from a prior forecast of 2.16 million. NRF vice president Jonathan Gold said the industry had expected peak season to be "mostly behind us by now." The Port of Los Angeles alone handled 2.9 million TEU from June through August, and October imports are still forecast to rise 1.7% year over year.
The forward-looking numbers sharpen the split. Upstream respondents expect inventory levels of 62.9 over the next 12 months, while downstream respondents predict 44.4, which would mean retailers shrinking their inventories. If that holds, manufacturers and wholesalers are carrying the build now with no guarantee their customers will want the same volume next year. The overall 12-month outlook diverges too, at 68.6 upstream against 57.9 downstream.
Company size matters almost as much as position in the chain. Firms with fewer than 1,000 employees reported warehousing capacity at 36.0, compared with 44.1 for larger firms, a difference the report calls marginally significant. Their inventory costs ran at 82.7 against 75.8. Larger shippers tend to hold long-term leases and multi-site networks, while smaller ones are more likely to buy space on short terms in the very market that is tightening.
Trucks offer no relief. Transportation prices rose 2.7 points to 92.7, and transportation capacity fell 5.6 points to 34.4, its tenth straight month of contraction. The LMI report ties the price surge to fuel, citing an average U.S. diesel price of $6.832 per gallon in late September, the second-highest weekly reading on record. When storage is full and moving goods out costs more each week, the cost of every delayed handoff between partners compounds.
Warehousing capacity is predicted to recover to 50.6 over the next 12 months, essentially neutral, so this is a peak-season crunch rather than a permanent shortage. That makes the next few weeks the expensive part. The playbook below reflects where the index data shows the pressure concentrating.
The September data does not describe a shortage of demand or a shortage of goods. It describes a shortage of room, concentrated in the part of the chain that has the least control over when stock leaves. The companies that get through the next several weeks well will be the ones that treat inventory location and partner timing as a cost line to manage, not a detail to sort out after peak season.

Guide
With upstream utilization at 68.4, holiday stock is waiting on partners to take it. Nulogy makes the case that brand owners and external partners working from shared schedules move inventory sooner and hold less of it.
Download

Report
A 14-point monthly drop in warehouse capacity is the kind of shock few annual plans budget for. GEP looks at the blind spots supply chain leaders underestimate and how resilient organizations prepare for them.
Download

Guide
With transportation prices at 92.7 and diesel near record highs, moving stock out of full warehouses is costly. Motive shows how bringing fleet, fuel and spend management onto one platform exposes where that money goes.
Download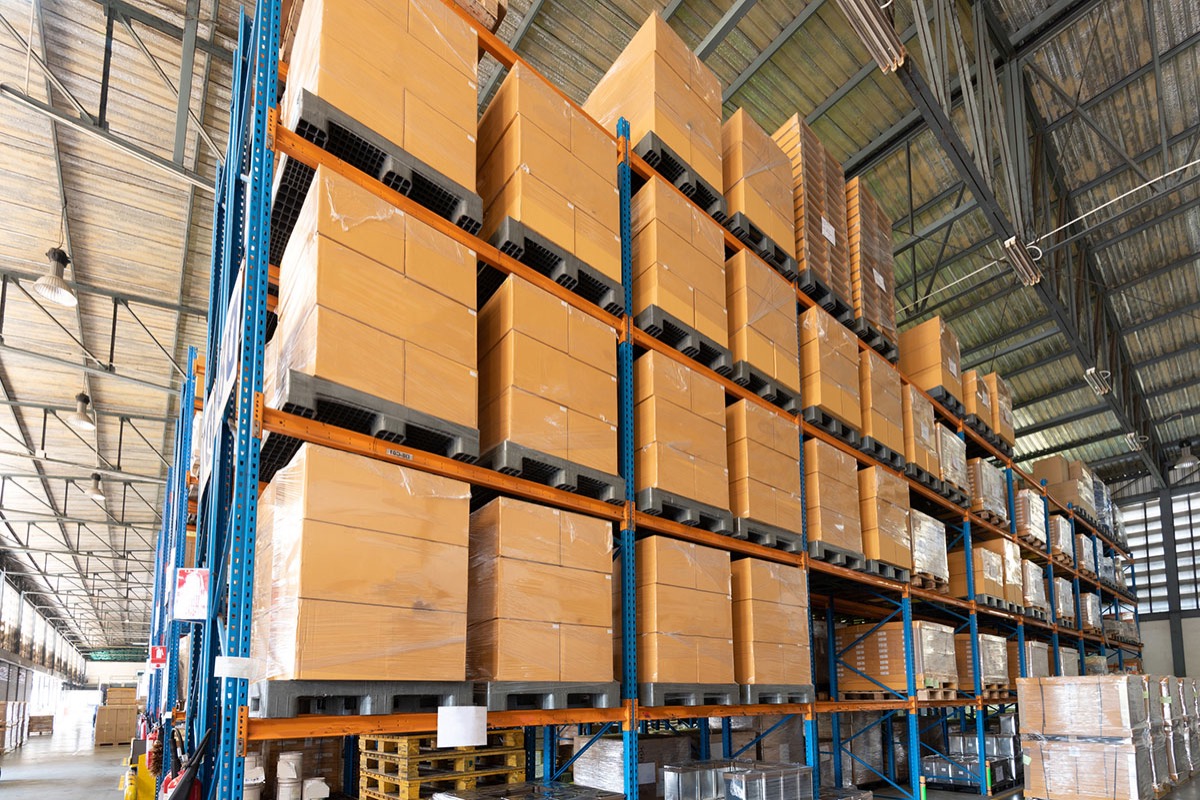
Aggregate logistics costs averaged 241.9 from March through August, above the 240 level that has historically preceded supply-driven inflation. Inventory growth is slowing, but holding it costs more than ever.
After years of lean inventory discipline, supply chain disruptions have forced a fundamental rethink. The companies that survived the last three years of volatility share a common trait: they stockpile strategically.
