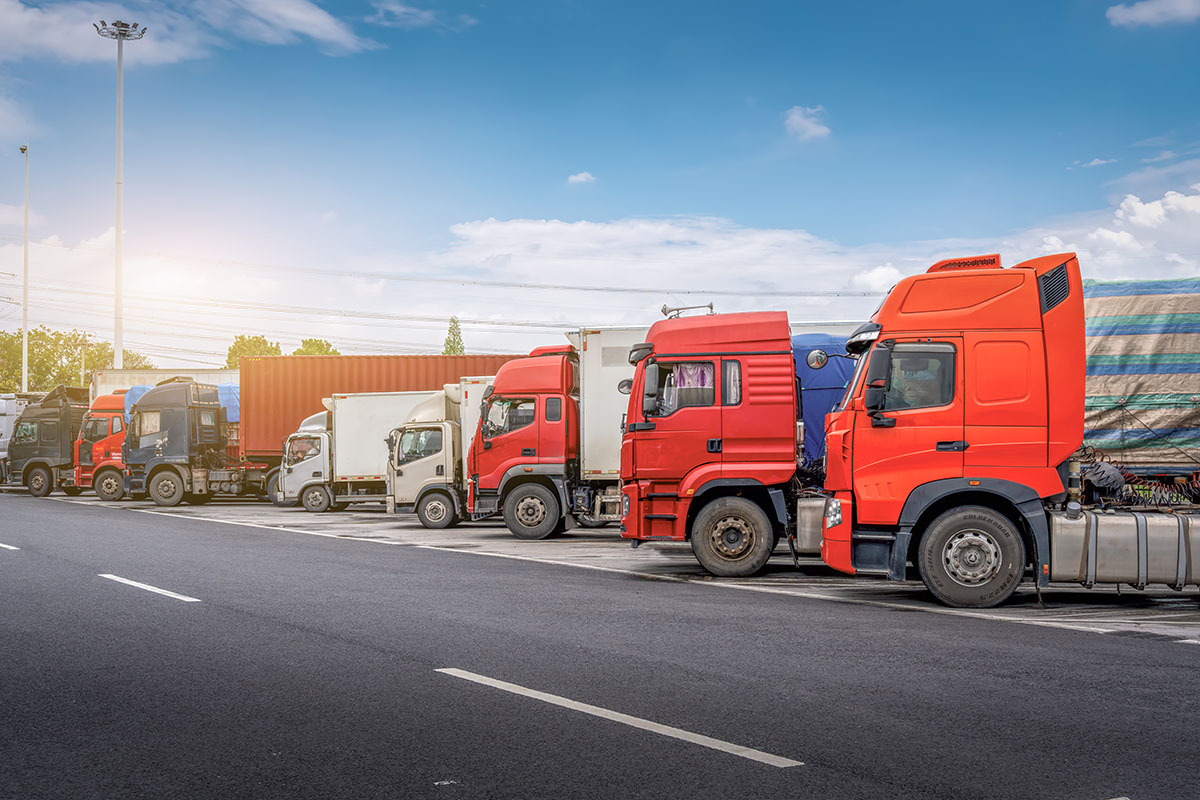
Shipments are down, yet shippers are paying far more to move them. Insurance costs, federal enforcement and tougher carrier vetting are pulling trucks off the road faster than freight demand is easing.
Key Takeaways
In a normal freight cycle, softer demand means cheaper trucks. That relationship has broken. Through the second quarter, shipments declined 2.8% year over year while the amount shippers spent to move them climbed 28.1%, according to the U.S. Bank Freight Payment Index figures compiled in Spot Inc's August 2026 logistics market update. Fewer loads, much bigger bills. The explanation is not a demand boom. It is a supply problem.
Spot rates have cooled since peaking in early July, and the early import rush that retailers staged ahead of tariff changes is winding down. Yet the structural pressure has not let up. The trucks that left the market over the past year are not coming back quickly, and the reasons they left (insurance, enforcement and liability) are still intensifying.
The clearest signal is in how often carriers say no. National truckload tender rejections reached 14.36% in Spot Inc's August reading, well above the six-month average of 10.9%, with flatbed at 23.5% and reefer at 19.46%. The Logistics Managers' Index transportation capacity reading fell to 28.4 in July from 30.8 in June, deep in contraction territory. Load-to-truck ratios for dry van stood at 10.38, against 5.45 a year earlier.
Contract networks are feeling it too. In its September 2026 North America truckload update, C.H. Robinson reported average route guide depth of 1.35 in August, meaning shippers typically went beyond their primary carrier to cover a load. Long-haul lanes over 600 miles averaged weekly route guide failures of 8.5%, compared with 3.6% on short hauls under 400 miles. The company forecasts 2026 truckload rates up 30% year over year for dry van, 31% for refrigerated and 28% for flatbed, followed by increases of roughly 10% to 11% across all three in 2027.
That 2027 outlook is the one procurement teams should study. It assumes rates keep climbing even as spot pricing eases, because, in C.H. Robinson's words, elevated insurance costs, stricter driver requirements and federal enforcement actions "continue removing capacity from the market." In other words, the carrier base is shrinking on its own schedule, largely independent of how much freight is moving.
Insurance is the pressure point carriers mention first. "Insurance remains one of the fastest-growing operating expenses, with several carriers reporting double-digit increases and significantly higher deductibles," C.H. Robinson noted. The liability backdrop explains why. Writing in FleetOwner, NationaLease senior vice president Jane Clark pointed to data showing nuclear verdicts rose 52% in 2024 to 135 cases totaling $31.3 billion, while the federally mandated minimum insurance level has been frozen at $750,000 since 1985. For a small fleet, one catastrophic claim can outrun its entire coverage, and underwriters are pricing accordingly. As Clark put it, insurance is "becoming a defining factor in whether many carriers can stay on the road."
Enforcement is the second squeeze. The Federal Motor Carrier Safety Administration published a proposed rule on August 10, 2026 that would formally make failure to meet English language proficiency standards an out-of-service violation, with comments due by October 9, according to the Commercial Vehicle Training Association. The requirement itself dates to 1937; what is changing is that roadside enforcement will now take noncompliant drivers off the road immediately. Separately, the late-July Operation Highway Shield enforcement push removed more than 750 unsafe trucks or drivers, Spot Inc reported.
The third force is quieter but may matter most: brokers and shippers are tightening who they will tender to. FreightWaves reported on September 17 that Schneider National's brokerage unit has reduced its approved carriers from 60,000 to 14,000, with executives citing a broker liability ruling that has raised the stakes of carrier vetting. Werner Enterprises forecast one-way truckload rate increases of 10% to 13% year over year for the third quarter and expects "strong" contract rate increases during the 2027 bid season. Both carriers described the capacity correction as still in its early stages.
Capacity scarcity, not freight demand, is now the primary constraint on growth for the largest truckload carriers, according to executives at Schneider and Werner. FreightWaves, September 17, 2026
Put those three forces together and a pattern emerges. The carriers that remain in the market, and that brokers are willing to keep on approved lists, are the ones that can prove their safety performance with data. A documented safety program is no longer just a way to reduce crashes. It is what keeps insurance affordable, keeps drivers compliant at roadside inspections, and keeps a carrier eligible for freight that shippers and brokers now vet far more carefully.
For shippers, the implication is that capacity planning has become partly a safety due diligence exercise. A cheaper carrier that loses its coverage or fails an out-of-service inspection mid-season is not cheaper. And with C.H. Robinson noting that carriers increasingly prefer dedicated and round-trip freight over transactional loads, shippers that offer consistent, well-planned volume are better placed to secure trucks than those relying on the spot market.
Private fleets face the same arithmetic. FreightWaves reported that rising insurance costs and record replacement cycles are pushing some private fleets toward dedicated carrier conversions, which adds yet another source of demand for the carriers left standing.
The freight market is sending a message that runs against intuition: cooling demand is not a signal to relax. The trucks that disappeared over the past year were removed by cost, liability and regulation, and none of those pressures is easing. Shippers who treat carrier safety and reliability as core procurement criteria will be the ones still getting their freight moved when the 2027 bids come due.

Guide
With insurers raising premiums and deductibles on every renewal, a documented safety program is what keeps a fleet insurable. This guide lays out a step-by-step framework for cutting incident rates and building the safety data underwriters and brokers now ask for.
Download

Guide
When carrier vetting tightens and liability costs climb, safety performance and cost discipline decide which fleets stay on approved lists. Six field-tested strategies from fleet managers on improving both at the same time.
Download

Guide
Freight costs rising 28% on falling volumes is exactly the kind of shock that breaks rigid supply plans. This playbook covers demand variability, supplier risk and the operational agility shippers need when transportation capacity becomes the constraint.
Download
Companies are racing to move production closer to home markets, and freight patterns across North America are shifting faster than most carriers anticipated. We spoke with the shippers and 3PLs driving the change.
After years of lean inventory discipline, supply chain disruptions have forced a fundamental rethink. The companies that survived the last three years of volatility share a common trait.
A sweeping realignment of global freight flows is underway. Trade policy shifts, carrier consolidation, and nearshoring momentum are combining to redraw where goods move.
